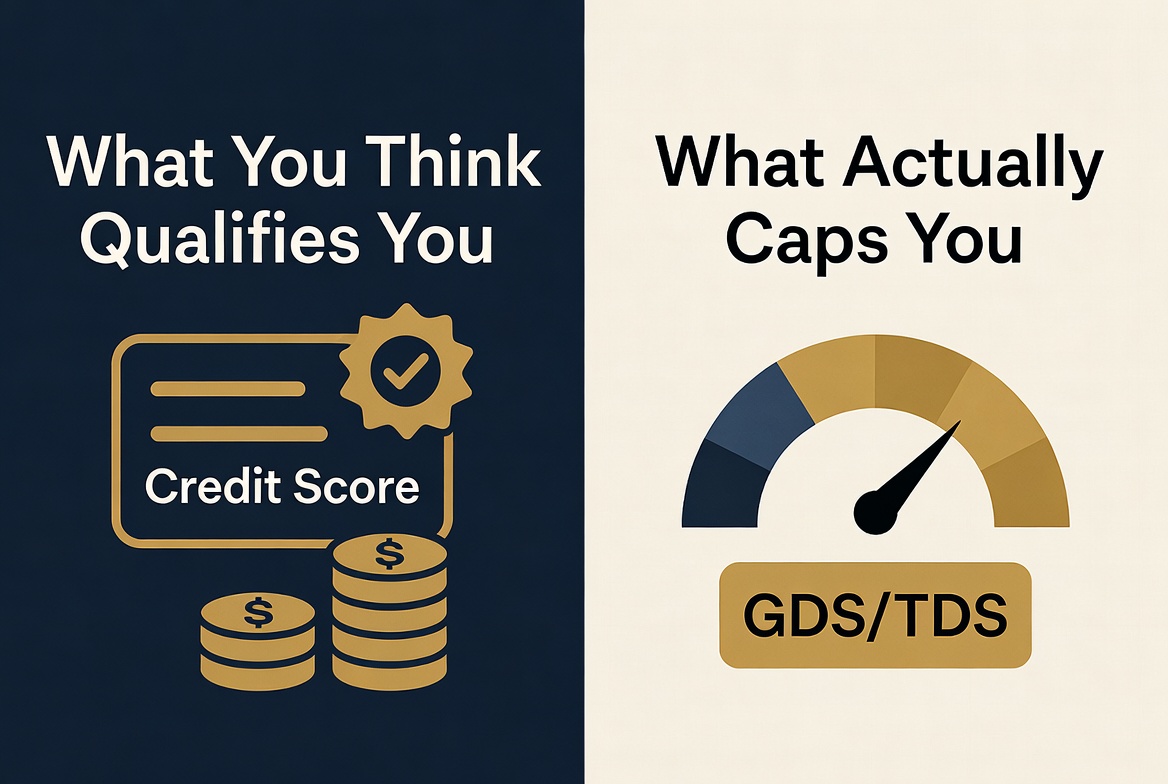
Ask most people what determines how much house they can buy, and you'll hear two answers: credit score and down payment. Both matter. Neither is the number that actually decides your ceiling. The number that does the real capping almost never comes up until you're already deep into the process — sometimes not until an offer is already in.
It's called your debt service ratio, and lenders use it every single time, on every single application. It's not a secret. It's just rarely explained, because it's boring math instead of a headline number like your credit score.
Two Ratios, One Job: Finding Your Ceiling
Lenders actually calculate two of them:
- GDS (Gross Debt Service): your housing costs — mortgage payment, property taxes, heat, and half your condo fees if applicable — as a percentage of your gross monthly income.
- TDS (Total Debt Service): the same housing costs, plus every other debt payment you carry — car loans, credit cards, lines of credit, student loans — as a percentage of that same income.
Most lenders want your GDS at or below 39% and your TDS at or below 44%. Go over either one, and it doesn't matter how good your credit score is or how big your down payment is — the lender caps your mortgage amount right there.
Your credit score tells a lender whether you pay your bills on time. Your debt service ratio tells them whether you can actually afford the bill in the first place. Only one of those decides your number.
Why This Catches First-Time Buyers Off Guard
Here's the pattern I see constantly: a buyer has a strong credit score, a healthy down payment, and feels confident going into a purchase. Then a car lease or a chunk of credit card debt quietly eats into their TDS room, and the number they qualify for comes in well below what they expected — sometimes tens of thousands of dollars below.
It's not that anything went wrong. It's that nobody explained the number that was actually running the show the whole time.
A Real Example — Halifax, 2026
| Household gross annual income | $95,000 |
| Monthly gross income | $7,917 |
| Maximum GDS room (39%) | $3,088/month |
| Maximum TDS room (44%) | $3,483/month |
| Existing car loan + credit card min. payments | $610/month |
| Actual housing budget the TDS allows | $2,873/month |
That $610 monthly obligation didn't just cost this buyer $610 — it dropped their effective housing budget by that same amount every month, which translates into real purchase-price room lost. That's the part nobody sees coming until the numbers are already run.
What You Can Actually Do About It
- Get your ratios calculated before you shop — not after you've found the house. A proper pre-approval runs both GDS and TDS against your real numbers, not a rough estimate.
- Pay down or pay off small revolving debt before applying — even a few hundred dollars a month back in TDS room can meaningfully change your ceiling.
- Know the difference between pre-qualified and pre-approved — a pre-qualification is often based on self-reported numbers and may not reflect your real ratios at all. (I wrote about that difference here.)
- Ask directly what your ratios are — any broker or lender running your file should be able to tell you both numbers, not just your approved amount.
This isn't a number designed to trip you up. It's the actual measuring stick your lender is using the whole time — you just deserve to see it before you fall in love with a house it won't support.