A buyer came to me two weeks before closing. Bank financing had fallen through — appraisal came in low, underwriting flagged something last minute, file got stuck in a queue. Doesn't really matter which. The outcome's the same either way: a firm closing date, no financing, and a seller who isn't waiting around.
Here's the thing people get wrong about that situation: the fix isn't a faster bank. Banks don't move faster under pressure — they move slower, because more moving parts means more that can hold things up. Multiple underwriting reviews, committee approvals, conditions stacking one after another. None of that is a flaw in the system. It's just not built for two weeks.
Private financing is built differently. The decision comes down to fewer, clearer things: the equity in the property, and a workable exit strategy. When those two things check out, a file can move in days instead of weeks — not because anyone's cutting corners, but because there are simply fewer steps to move through.
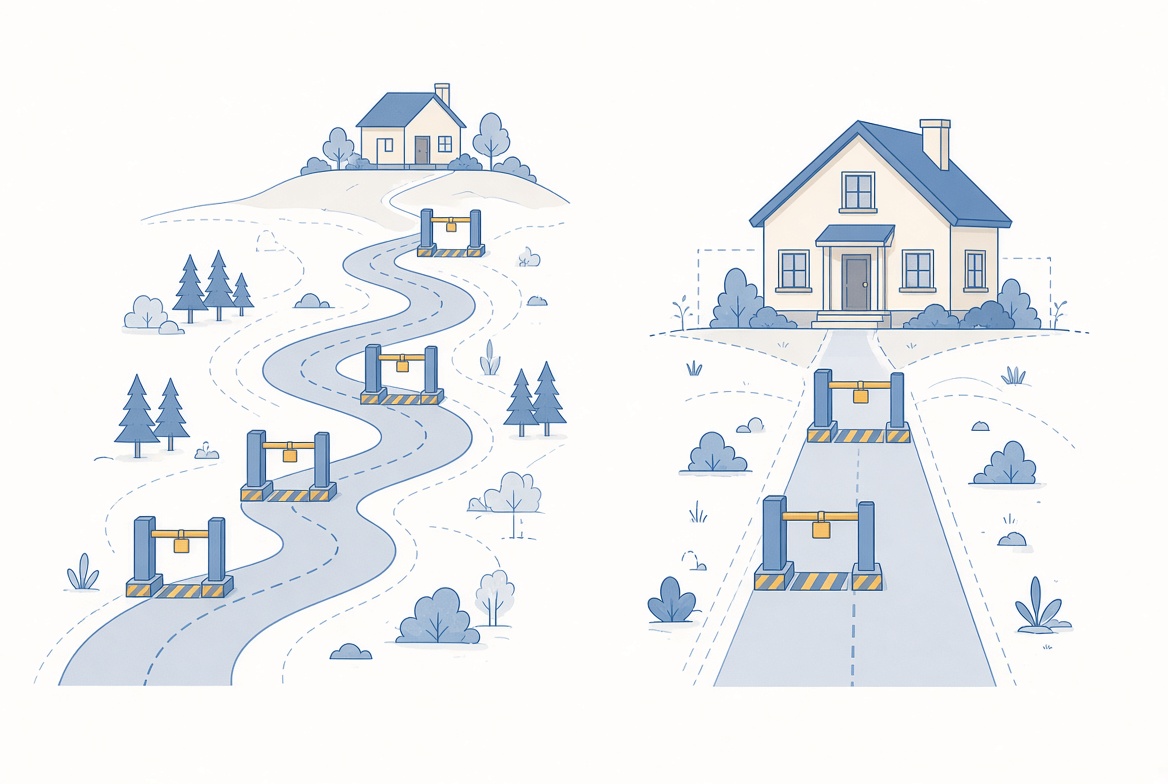
That's the piece people miss. Fast isn't risky here. Fast is what happens when the process is simpler by design, not rushed under pressure.
What actually saves a closing like that:
- A clear equity position — enough room in the property value that the risk is straightforward to assess
- A real exit strategy — a plan to refinance with a conventional lender once the immediate issue is resolved, not just "we'll figure it out later"
- A file put together properly from day one — appraisal, application, and payout details all lining up cleanly, so there's nothing to go back and question
When those three things are in place, private financing isn't a last resort. It's just the right tool for a timing problem — the same way a bank mortgage is the right tool when timing isn't the constraint.
If a deal is on the clock and the usual path isn't going to make it in time, that's exactly the kind of file I want to see.